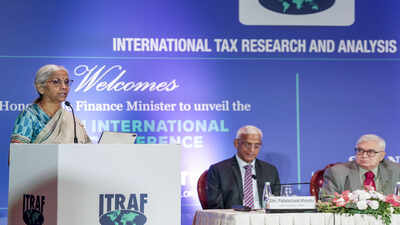
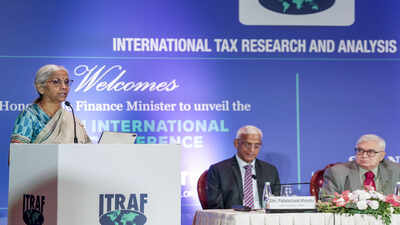
Finance minister Nirmala Sitharaman on Wednesday said India has renegotiated its tax treaties with Mauritius, Singapore and Cyprus to restore the country’s right to tax capital gains arising from investments in India at the source.Speaking about India’s tax policy and international taxation framework, Sitharaman said the changes were part of wider efforts to strengthen the country’s tax base and prevent the misuse of treaty provisions.Under the earlier arrangements, investors based in some jurisdictions, particularly Mauritius, could in certain circumstances claim that capital gains from the sale of shares in Indian companies were taxable only in their country of residence. This effectively limited India’s ability to tax such gains.The India-Mauritius tax treaty was amended through a protocol signed in 2016, shifting the taxation of capital gains on shares acquired on or after April 1, 2017, towards the source country, India. Investments made before that date were grandfathered under the earlier provisions.Similar changes were made in India’s tax treaties with Singapore and Cyprus. The amendments were accompanied by provisions aimed at preventing treaty abuse, including limitations on benefits available to entities that were established primarily to obtain tax advantages.
How important do you think it is for India to have the right to tax capital gains from foreign investments?
3k+ users shared opinion today
5k+ users already voted today
3k+ users shared opinion today
The changes followed longstanding concerns over the use of treaty jurisdictions for routing investments into India and potentially reducing or eliminating tax liabilities. The Supreme Court, in a 2026 ruling involving Mauritius-based investors, also examined the evolution of India’s treaty framework and noted that the 2016 Mauritius protocol had shifted the taxation of relevant capital gains from a residence-based system to a source-based one.