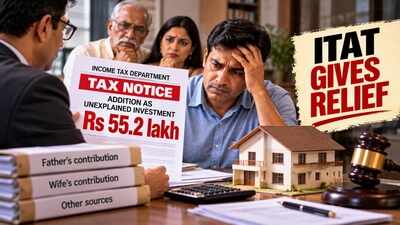
A man bought a residential property along with his wife and father. However, he did not file his income tax return for the year.The tax department opened his case for reassessment and adding Rs 55.2 lakh as unexplained investment. The Mumbai bench of the Income Tax Appellate Tribunal (ITAT) deleted the Rs 55.2 lakh addition made to a taxpayer’s income. Here’s what the case is about:
What the case is about
A man bought a residential property jointly with his wife and his father. The Income Tax Department reopened his assessment for the 2016-17 assessment year after receiving information through its Risk Management Strategy that he had purchased an immovable property during the 2015-16 financial year. The assessment proceedings recorded that he had not filed an income tax return for the relevant year.Also Read | Wife sold shares for Rs 8.31 crore LTCG, bought husband’s Mumbai property for Rs 7.5 crore and claimed Section 54F exemption; taxman calls it tax avoidance, but ITAT Mumbai gives relief to herDuring reassessment, the man explained that the property had been funded through several sources, including a Rs 32 lakh housing loan from a bank and contributions from himself and his family members. The assessing officer accepted the housing loan but considered that the remaining investment was insufficiently explained.The officer calculated the addition using total payments of Rs 87.2 lakh and deducted the accepted housing loan of Rs 32 lakh, treating the balance of Rs 55.2 lakh as unexplained investment under Section 69 of the Income Tax Act, read with Section 115BBE.The National Faceless Appeal Centre upheld the addition. It found that the evidence submitted at that stage did not adequately establish the sources of the contributions attributed to the man’s father and wife.The man then approached the ITAT, challenging both the addition and the calculation underlying it. He argued that the property was jointly owned and that the payments had come from identifiable sources. He also disputed the assessing officer’s use of Rs 87.2 lakh, contending that the actual payments, including VAT, were Rs 84 lakh.Before the tribunal, the man submitted additional documents, including bank statements, employment and remuneration records, and material relating to his father’s pension and funds.Also Read | Delhi couple repaid Rs 1.41 crore home loan, but the bank lost their original sale deed property papers; consumer commission orders Rs 15 lakh compensation plus Rs 50,000 costs
Why did ITAT delete the tax additions ?
The bench examined the additional evidence submitted by the man, including banking records and documents concerning the family members’ financial contributions.It found that the payments towards the property could be identified and were supported by documentary material. The evidence also established that the property had been purchased jointly, rather than solely by the man.According to the judgement, the assessee explained the sources towards the acquisition as a housing loan of Rs 32,00,000/-, contribution by his father of Rs 11,20,000/-, contribution by his wife of Rs 20,00,000/-, his own funds of Rs 1,70,000/- and further funds of Rs 19,10,000/-.The tribunal considered the housing loan, the taxpayer’s own funds and the contributions attributed to his wife and father in the context of the records placed before it.The significance of the additional evidence was that it addressed the gaps in the explanation that the lower authorities had relied on when making and sustaining the addition.Also Read | Son claimed share in mother’s Delhi house, saying he paid Rs 1.5 lakh for land and Rs 60,000 for construction; Delhi High Court rejects claim, orders him and wife to vacateThe calculation of the investment was another important issue. The agreed consideration recorded for the property was Rs 80 lakh. The man contended that actual payments, including VAT, were Rs 84 lakh, while the assessing officer had used Rs 87.2 lakh to calculate the unexplained investment.The tribunal found that the higher figure adopted by the assessing officer was not substantiated by the documents on record. The discrepancy mattered because the Rs 55.2 lakh addition had been calculated by deducting the accepted housing loan from the higher payment figure.The tribunal held that the investment could not be treated as unexplained in the manner adopted by the assessing officer.The tribunal therefore deleted the Rs 55.2 lakh addition under Section 69 read with Section 115BBE.According to Raghav Bajaj, Partner at Khaitan & Co, the ruling restates an important principle: Section 69 is not a tool for presumptive attribution.Before an investment can be taxed as unexplained, it must first be established that the taxpayer has made an investment, and only then ask whether its source has been satisfactorily explained.The immovable property was bought jointly by a son, his father and his wife. It was financed through a joint housing loan and paid for through traceable bank transfers from each of their accounts.“Despite this, the entire balance was attributed to one co-owner by the tax officer. The Tribunal held that an addition built on assumption, and on numbers that cannot be reconciled with the actual payments evidenced by documents, is not valid,” Bajaj explains.Also Read | Woman declared Rs 67.4 lakh ancestral jewellery in her ITR which led to additions by tax department; ITAT Mumbai deleted it on basis of old records, but rejected her Rs 12 lakh HUF brokerage claim
Significance of ruling
The decision matters well beyond its facts. Pooling salaries, pensions, savings and inherited funds to buy a home is a familiar reality for Indian families, and this ruling recognises each such contributor’s role, Bajaj tells TOI.At the same time, the case is a cautionary tale – taxpayers should keep a clear, person-wise record of contributions from the day of purchase in similar facts.“Further, it must also be noted that analytics-led reassessments are a legitimate and efficient way to identify high-value transactions, but a data flag is the beginning of an inquiry, not its conclusion. Where title is shared, each co-owner’s sources must be examined on their own merits, and any addition must be confined to the share genuinely left unexplained,” Bajaj adds.However, according to him, one significant question remains open. The taxpayer also challenged the validity of the reopening itself, arguing that the income that could have escaped assessment did not exceed the Rs 50 lakh threshold relevant to the limitation provisions.“Having decided the case on merits, the Tribunal did not rule on that point. Taxpayers facing similar reassessments should therefore raise and preserve jurisdictional challenges from the outset, alongside a well-documented defence on merits,” he says.Also Read | Man enters JDA for land, gets 6 flats from builder and transfers 5 to wife, but gets tax notice; ITAT Delhi deletes Rs 4.14 crore additions after finding no stock-in-trade conversion or sale