The Reserve Bank of India has announced a repo rate hike to keep inflation under check. But already faced with higher costs of daily essentials, Indian households have to now contend with paying higher EMIs for their loans.The US-Iran war has fed into higher costs for daily use items and the impact is visible in retail inflation numbers which are steadily rising. To keep inflation under 6%, RBI-led Monetary Policy Committee has opted for a 25 basis points repo rate hike in its review on Wednesday.
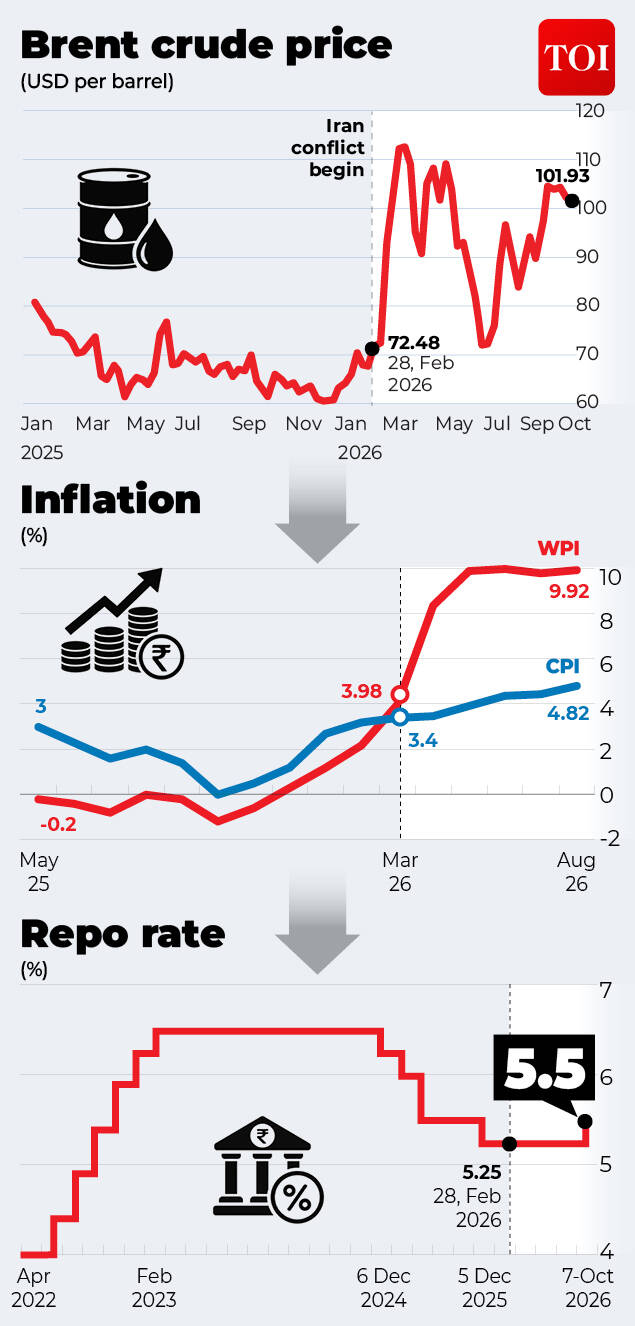
Global oil price hike has led to higher inflation, which in turn has prompted RBI to hike repo rate
But why does a hike in repo rate hit your pocket? Is it better for you to opt for an EMI hike or an extension of your loan tenor? And how does this step from RBI help people looking to invest in fixed deposits? We decode:
What happens to your loan EMI and tenor?
The math works like this: RBI will now lend money to banks at a higher rate. Banks will in turn charge customers higher interest rates to make up for the higher borrowing costs they face. This means loan rates will go up.
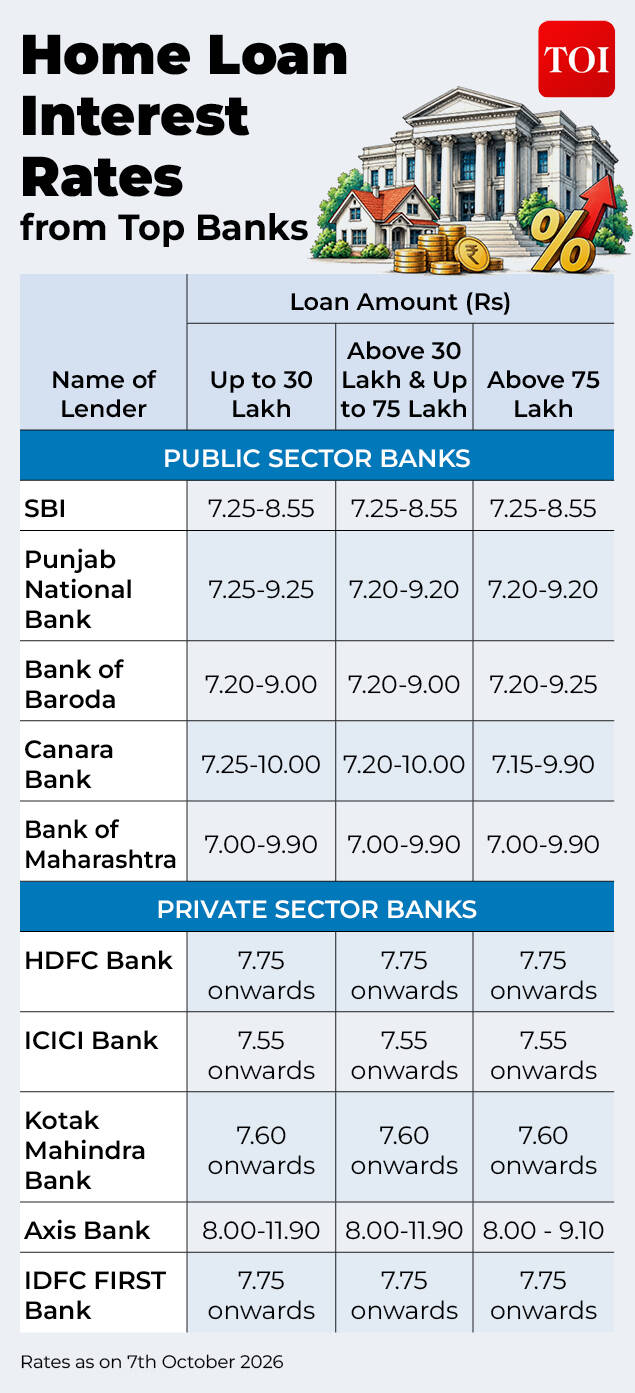
Current Home Loan Interest Rates
So, does the repo rate hike mean an automatic increase in your loan EMIs? Only if your loan is linked to a floating rate.According to Santosh Agarwal, CEO of Paisabazaar, floating-rate home loans will become more expensive due to the increase in repo rate. Borrowers should first check the reset date of their home loans to know when the impact would come into effect.First let’s understand what the impact of the 25 basis points hike is on your monthly EMIs and your total interest outgo if you decide to keep your loan tenor the same.
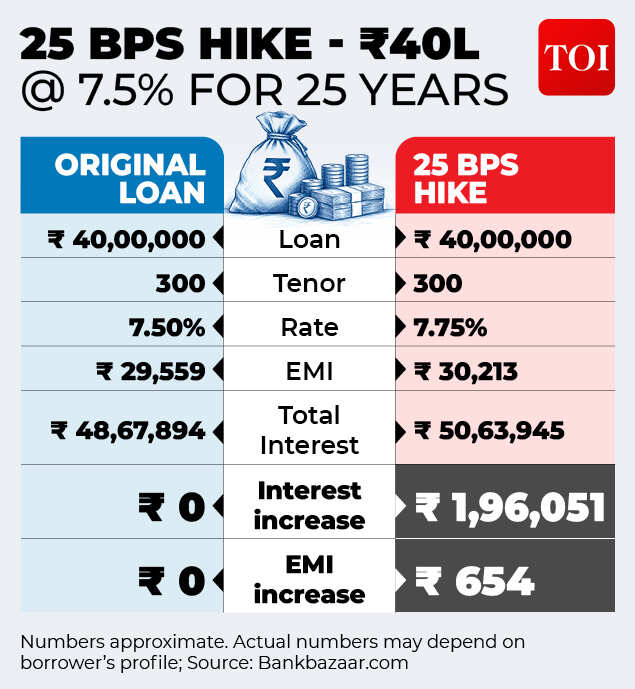
Impact of 25 bps rate hike on Rs 40 lakh loan
In this example shared by Bankbazaar, the increase in interest outgo is visible for loans of Rs 40 lakh, Rs 50 lakh, and Rs 60 lakh across the loan tenor. While the rise in your monthly EMIs may appear to be small, the total impact over a loan tenor is considerable.
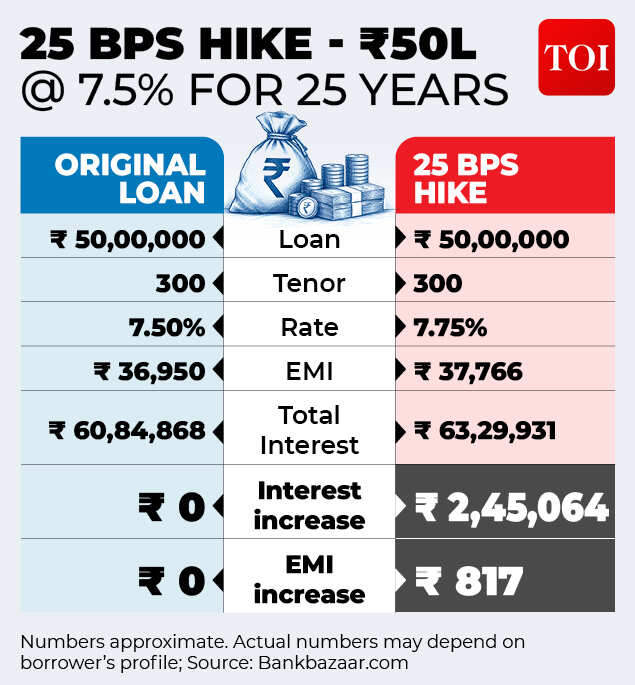
Impact of 25 bps rate hike on Rs 50 lakh loan
For example, if you take the loan before the rate hike, your interest outgo would be Rs 4,867,894 for a Rs 40 lakh loan. But with a hike, this would rise to Rs 5,063,945, which is an increase of Rs 1.9 lakh! For a Rs 50 lakh loan, this interest payment may rise by Rs 2.45 lakh, and Rs 2.94 lakh for a Rs 60 lakh loan. The hike would be much higher if the interest rates keep rising.
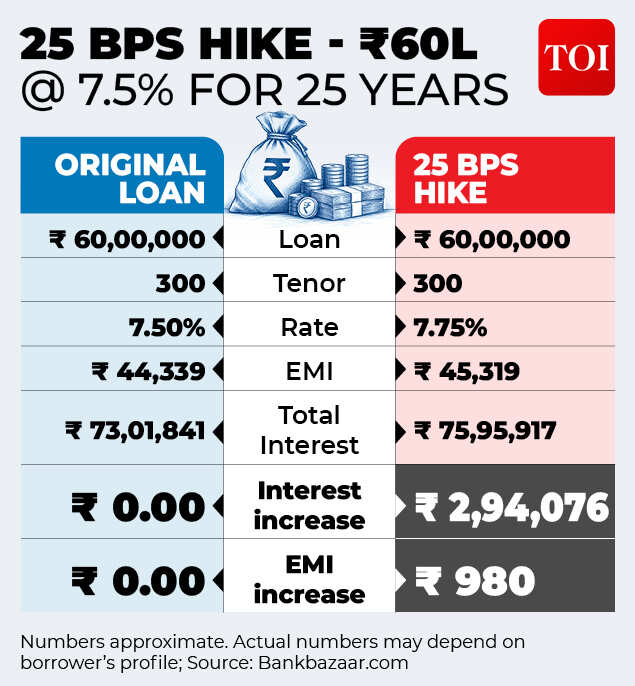
Impact of 25 bps rate hike on Rs 60 lakh loan
When the repo rate rises and the bank passes it on, the borrower has two ways to absorb it: pay a higher EMI over the same tenor, or keep the EMI unchanged and repay over a longer tenor.Now let’s take a scenario, where a borrower has a home loan of Rs 50 lakh, that is payable over a period of 20 years or 240 months and has a 8.5% interest rate that is linked to the repo rate. The monthly EMI works out to be around Rs 43,391. The total repayment amount over the loan’s tenor (including the interest payment) works out to be around Rs 1.04 crore.Vivek Iyer, Partner and Financial Services Risk Advisory Leader, Grant Thornton explains these two scenarios with examples assuming progressive hikes in repo rates:
- Extending the tenor is the costlier route. At a 100 bps hike, keeping the EMI unchanged costs about Rs 22 lakh more than raising the EMI, because interest keeps compounding over almost six extra years.
- Tenor grows faster than the rate. Each 25 bps adds more months than the one before, because a larger share of the fixed EMI goes to interest. Banks also cap how far a tenor can stretch, usually by the borrower’s age or a maximum term. Past that cap, the EMI has to rise anyway.
- The borrower decides. RBI requires banks to offer borrowers the choice between a higher EMI and a longer tenor when rates reset.
- If cash flow allows, raise the EMI. Where it doesn’t, a longer tenor combined with part-prepayments whenever surplus funds are available limits the extra interest, Vivek Iyer tells TOI.
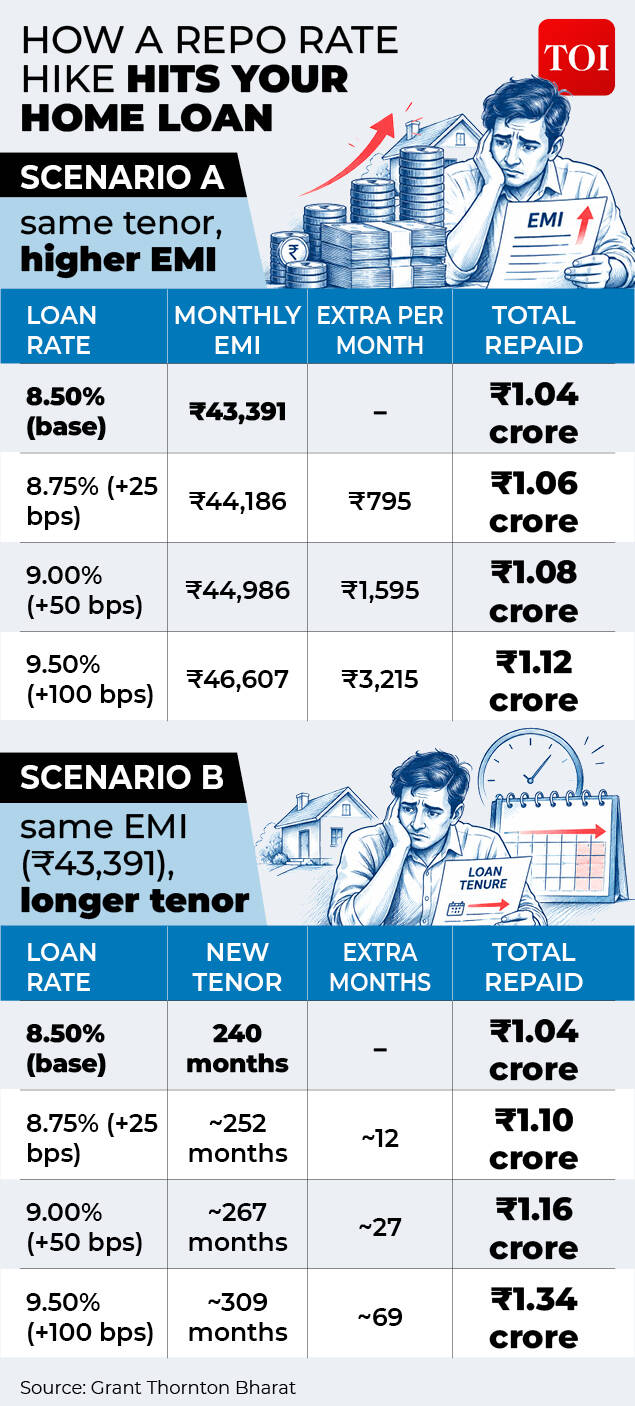
Impact of Multiple Repo Rate Hikes On EMIs & Tenor
The biggest thing to remember is that extending the tenor does not impact your EMI but increases the overall interest outgo and the cost of the loan.
Is it time to put money in FDs?
There is another side to a repo rate hike, which turns out to be beneficial for people looking to save their money through fixed deposits. Because the cost of borrowing increases for banks, they are willing to offer higher interest rates for fixed deposits to attract flows.This means a repo rate hike makes FDs attractive, but the advantage may not be immediate.Adhil Shetty, CEO, Bankbazaar sees the benefit for fixed deposit investors building gradually and not immediately.“Banks usually revise deposit rates in their own time, and new deposits get the higher rate first. Existing fixed deposits continue to earn the rate at which they were booked,” he tells TOI.“With the RBI also moving to calibrated tightening, savers can keep an eye on when their deposits mature, so that each one renews at the prevailing rate. Laddering FDs, by splitting money across deposits that mature at different times, also keeps part of the money accessible,” he adds.
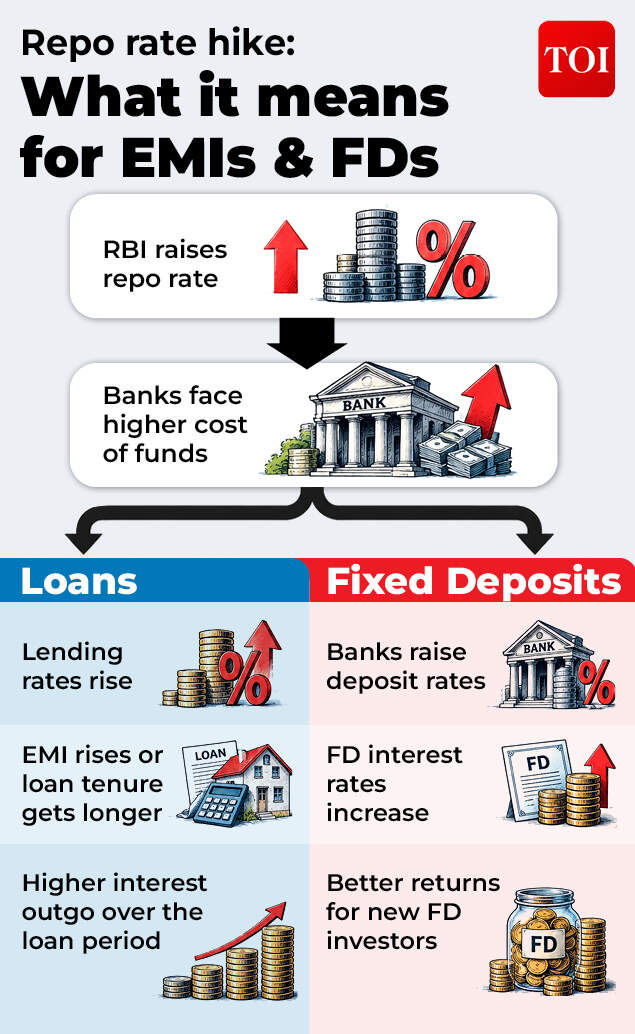
Repo rate hike- What it means for EMIs & FDs
Santosh Agarwal of Paisabazaar says that existing FD holders should not change the investment immediately.“If your FD is maturing soon or you want to make a fresh deposit, compare the latest rates across banks before reinvesting. Before locking in funds for a longer time, new FD investors might want to wait for banks to adjust their FD rates in response to the repo rate shift,” she tells TOI.So what is the net impact? What today’s rate increase means for you depends on whether you borrow, save or do both. If you have a home loan, the EMI would go up, adding to your total interest payout.“If you mainly save, the gains come later, when deposits are renewed or opened afresh. If you do both, the higher EMI and the higher deposit income work against each other, though the loan usually adjusts first. So, start by listing your loan balance, your savings and their rates. Then decide where spare money works harder, in cutting the loan or in a deposit,” says Adhil Shetty.(Disclaimer: Recommendations and views on the stock market, or any other asset classes or personal finance management tips given by experts and analysts are their own. These opinions do not represent the views of The Times of India.)