News Latest

New Recipe

Rishabh Pant ruled out of first two India A matches against New Zealand A, Kumar Kushagra named replacement | Cricket News

Cricketer Rishabh Pant (ANI Photo) Rishabh Pant’s injury has forced a change to India’s preparations for their upcoming red-ball tour of New Zealand, with wicketkeeper-batter Kumar Kushagra named as his replacement for the first two matches. Pant, who was initially selected subject to fitness, has been ruled out after sustaining a left-side strain during the...

‘Jailer 2’ advance booking: Rajinikanth and Nelson’s film crosses Rs 22 crore in worldwide pre-sales four days before its October 15 release |

Rajinikanth’s ‘Jailer 2’ is gaining momentum at the ticket counters as advance bookings open up ahead of its theatrical release this week. The sequel has drawn strong interest from audiences in India and overseas, raising hopes of one of the biggest Tamil film openings of the year. Directed by Nelson Dilipkumar, the film is set...

Gemini Horoscope Today, October 13, 2026: Clear thinking boosts productivity, communication and financial decisions

General:Spirit for Today. The Sun and Mercury add more to your thinking power allowing you to focus your concentration, even on a busy weekday, with the moon providing alertness and not feeling scattered.You will see a positive tempo in a few little things; responding timely to messages; completing errands without problems, recalling what someone had...

New RBI rules may end loan spread tinkering; to standardise rate setting across banks, NBFCs

Table of Content

Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry’s standard dummy text ever since the 1500s, when an unknown printer took a galley of type and scrambled it to make a type specimen book.

The Future of Gadgets

Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been standard dummy text ever since the 1500s,

Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry’s standard dummy text ever since the 1500s, when an unknown printer took a galley of type and scrambled it to make a type specimen book.


New RBI rules may end loan spread tinkering; to standardise rate setting across banks, NBFCs
The methodology used to calculate internal benchmarks will also have to be made publicly available

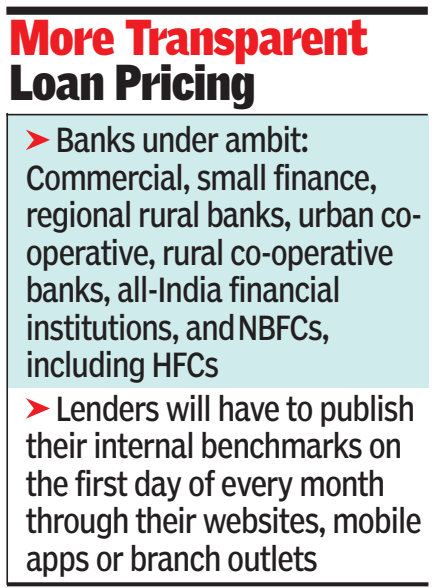
MUMBAI: Lenders may no longer be able to tinker with loan spreads over the benchmark rate to offer new borrowers better deals than existing customers. Draft RBI rules seeking to standardise interest-rate setting across banks, NBFCs and cooperatives require lenders to maintain the spread between the benchmark rate and the loan rate for at least three years.The proposed framework standardises interest calculation across lenders. Interest on advances will have to be charged on monthly rests, except for specified agricultural advances, and calculated on a daily reducing balance basis using the actual/actual day-count convention.
RBI loans

Smaller lenders will get exemptions from some of the requirements.

For floating-rate loans, the benchmark reset frequency for major lenders cannot exceed three months and must remain fixed for the tenor of the loan. The draft also sets common parameters for spread components and requires non-credit risk components to remain unchanged for three years.A credit risk premium can be changed only when there is a documented change in the borrower’s credit profile following a comprehensive review. Other components of the spread cannot be increased before three years from the first disbursement or the last revision. Lenders can reduce these components earlier for customer retention only on a non-discriminatory basis. Loans also cannot be priced below the applicable benchmark.For commercial banks, floating-rate personal loans and floating-rate loans to MSMEs will continue to be linked to an external benchmark. Banks can use the repo rate, treasury-bill yields, SORR or benchmarks published by FBIL.Internal benchmarks such as MCLR will have to follow a stricter methodology. MCLR must be based on a three-month moving average of the annualised weighted average cost of fresh domestic deposits and borrowings. The calculation must be system-generated and independently verifiable.For NBFCs, cooperative banks, RRBs and AIFIs, linking floating-rate loans to an external benchmark will remain optional. These lenders can link such loans to internal or external benchmarks.Smaller lenders will get exemptions from some of the requirements. RCBs with deposits of up to Rs 1,000 crore, Base Layer NBFCs and Tier 1 and Tier 2 UCBs will not have to comply with the three-month maximum reset frequency or the three-year freeze on revisions to non-credit risk components of spreads.The methodology used to calculate internal benchmarks will also have to be made publicly available. Loan agreements will have to specify the benchmark, reset periodicity and reset dates.

Source link

todaynewss.in

Leave a Reply

Your email address will not be published. Required fields are marked *

Trending

Popular

Top News

Latest News

Hot News

©2026 .Today Newss  All rights reserved.